Author: Shao Jiadian (Mankun Blockchain Legal Services)
“Which licenses do we need?” This is the first question payment companies ask when bringing stablecoin payment solutions to Hong Kong. The number of licenses cannot be directly derived from the product name; the key is what role the company plays on-chain and off-chain: does it collect payments for customers, or buy and sell stablecoins itself? Does it settle funds to merchants' bank accounts, or let merchants keep balances on the platform for continued use? Does the platform custody wallets and private keys for merchants?
A single payment may simultaneously pass through three stages: stablecoin, bank account, and platform balance, but this does not mean a single “crypto payment license” can cover them all. Fiat currency exchange and cross-border collection/payment involve MSO; whether merchant balances can be retained and continue to be used for payment involves SVF; only when the company itself operates virtual asset trading, controls customer assets, or issues stablecoins does the analysis enter VATP, VA Dealing, VA Custody, or Stablecoin Issuer Licence respectively. License determination must ultimately fall back on these specific business actions, rather than停留在“crypto payment”这个产品名称上。
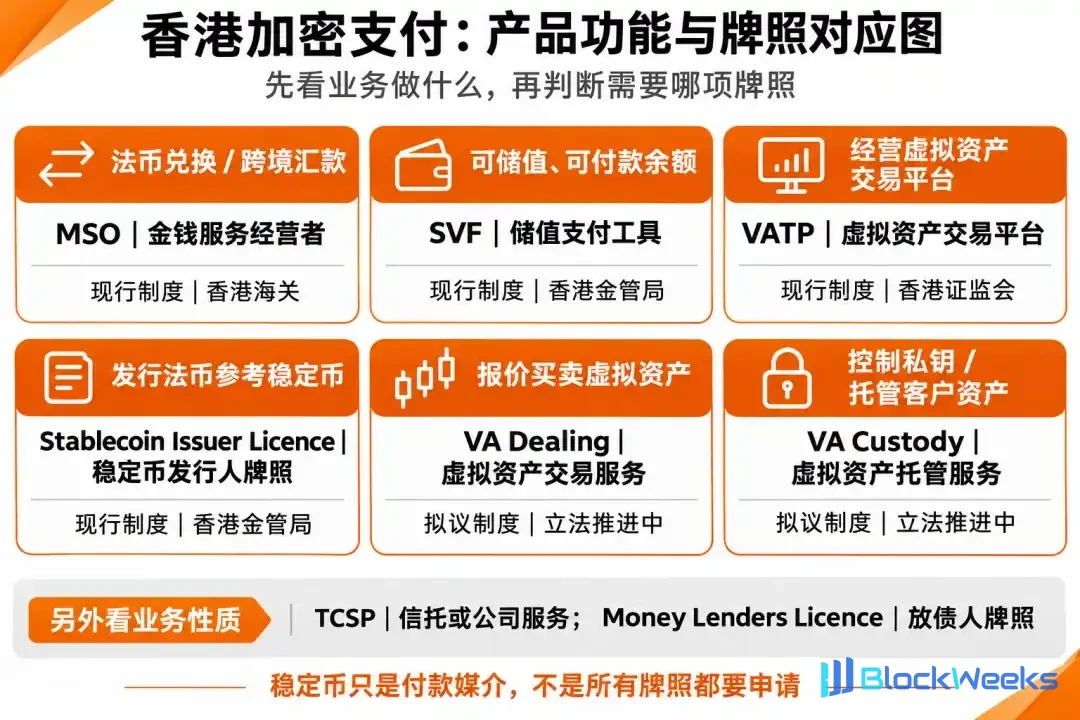
Figure: Panorama of Hong Kong crypto payment product functions and corresponding licenses
MSO and SVF correspond to two types of business arrangements respectively
Among payment products operating in Hong Kong, the Money Service Operator license (MSO) and the Stored Value Facility license (SVF) are usually the two major regulatory frameworks that first come into compliance view.
MSO covers fiat currency exchange and cross-border remittance
When stablecoin receipts land in a merchant's account, there is usually still an “off-ramp” step: the buyer pays stablecoin overseas, the platform or its settlement arrangement converts the value into Hong Kong dollars, and the merchant ultimately receives Hong Kong dollars in a bank account. For payment companies, the key judgment is not “which currency was used,” but whether the company accepts customer entrustment in Hong Kong to arrange this cross-border HKD collection and payment. The MSO license covers fiat currency exchange and remittance services, including sending or arranging to send funds overseas, receiving or arranging to receive funds from overseas, and arranging to collect funds overseas. The bank handles the final transfer, which does not automatically remove the payment company from the transaction chain.
There is an easily confused point here: converting stablecoin into Hong Kong dollars is not equivalent to “currency exchange” in the MSO sense. MSO regulates exchange and remittance between fiat currencies, and holding an MSO does not automatically grant authorization for stablecoin trading or virtual asset transactions. In other words, a payment company may need to handle two separate lines: the buying or exchange on the coin side, and the collection, remittance, and settlement on the HKD side. Whether the latter line falls under MSO depends on whether the company collects money for customers, arranges cross-border payments, or promises customers when HKD will arrive.
If the company itself undertakes HKD collection and cross-border remittance, it should prepare according to MSO application requirements, with emphasis on compliance officers, anti-money laundering processes, and bank accounts; if the company chooses to cooperate with an MSO already licensed in Hong Kong and outsource the HKD settlement part, it must also examine what responsibilities each party bears under the actual contract to ensure the partner's business scope can cover this arrangement.
SVF is not necessarily triggered just because there is a balance
The merchant has sold the goods, and the platform has received the money. Is this money immediately transferred to the merchant's bank account, or does it first stay in the platform account, allowing the merchant to use this balance to pay supply chain payables, advertising fees, or even employee salaries? This is the key dividing line that determines whether SVF (Stored Value Facility license) is involved.
The core logic of SVF is fund retention plus subsequent payment functionality. If the platform allows merchants to keep balances in the account, and this balance can be used to initiate new payments to third parties, then it already has the prototype of a stored value facility. For many startup payment teams, the SVF threshold is quite high: paid-up share capital of at least HKD 25 million, and the HKMA has very strict requirements for applicants' capital strength, risk management, and independent fund custody. Many companies using Hong Kong as their first overseas stop often cannot afford this cost in the early stage.
For this reason, many payment solutions intentionally avoid SVF in product design: after the merchant receives payment, the platform only provides settlement instruction transmission, and funds are directly settled within a specified time to an external bank account under the merchant's name, without forming a transferable fund pool within the platform. If the merchant needs to make external payments, it goes through a separate remittance process again, rather than directly transferring the incoming balance to the next party. This contraction in product logic often saves a great deal of time for compliance implementation.
Other licenses depend on whether the product has entered the corresponding business
In addition to basic payment and settlement, if the product further extends into trading, issuance, or lending, it will trigger licensing regulation in other dimensions.
VATP applies to operating a virtual asset trading platform
The appearance of stablecoins in payment solutions easily brings to mind the Virtual Asset Trading Platform license (VATP). But in actual business, most payment companies do not need to, and rarely proactively apply for, a VATP.
VATP regulates platforms that provide customers with automated matching of virtual asset transactions, centralized buying and selling, and custody, and is closer to the business model of an exchange. The role of an ordinary payment company is usually a service provider, not an exchange. If the platform only accepts stablecoins paid by customers, converts them into fiat currency according to external quotes, and pays the merchant, and there is no trading market in the entire process where buyers and sellers can freely place orders and match, then it will not fall within the scope of existing VATP regulation.
Turning payments into a “small exchange” is often the result of distorted compliance actions: for example, to allow merchants to freely choose the timing of currency exchange, the platform builds an internal matching mechanism in the background; or to improve exchange efficiency, it acts as a market maker and provides instant quotes to users within the platform. Once this step is taken, the compliance burden brought by the virtual asset trading business must be faced squarely.
The stablecoin issuer license corresponds to issuance and redemption
After the Legislative Council passed the Stablecoins Ordinance in May 2025, Hong Kong established a separate licensing regime for fiat stablecoin issuers. It should be clarified that using stablecoins in payment products and issuing stablecoins oneself are completely different matters.
In crypto payments, the vast majority of cases use mainstream stablecoins already circulating in the market as settlement tools; the stablecoin issuer license targets entities that issue stablecoins to the public and promise redemption in fiat currency at par value. The HKMA has extremely high thresholds for issuers' full high-quality reserve assets, local entity establishment, independent custody, and continuous auditing. If a payment company only embeds stablecoins into the acquiring or settlement process, there is no need at all to set the license target on an issuer. A more realistic approach is to choose stablecoins that meet Hong Kong's future regulatory expectations, pay attention to the HKMA's published list of compliant stablecoins and intermediary guidelines, and ensure that the currency underlying the product is itself compliant.
The money lenders license is used for operating merchant loans
The Money Lenders Licence is usually not on the payment team's first-round license list, but if the product solution includes “advance settlement” or “merchant installments,” it may become relevant.
Some payment solutions, in order to attract large merchants, provide early settlement services: before the merchant's payment has been cleared back from overseas, the platform advances the funds itself, and later deducts fees and principal from the actual received funds. If this advance evolves into a paid financing arrangement, or the platform directly provides merchants with short-term loans secured by future receivables, it may enter the boundary of money lending business. Hong Kong's money lending business is governed by the Money Lenders Ordinance and jointly administered by the Police and the Companies Registry. If a payment company wants to provide such value-added services, it must either obtain a money lenders license itself or cooperate with an already licensed money lending institution to avoid conducting lending business without a license.
Currency exchange and custody are where payment products most easily cross the line
Under the existing regime, what payment solutions most easily miss is actually not MSO or SVF, but virtual asset buying and selling and custody, two areas where regulation is currently tightening.
Under Hong Kong's existing legal framework, if a company buys and sells virtual assets with customers as principal in a transaction, or provides over-the-counter (OTC) exchange services, it is currently in a transitional period during which the HKMA and the SFC are formulating a new licensing regime. According to the consultation conclusions of the Financial Services and the Treasury Bureau and the SFC, Hong Kong will in future introduce separate licensing regimes for virtual asset dealing services (VA Dealing) and virtual asset custody services (VA Custody). This means that if a payment company both collects stablecoins on behalf of customers and itself acts as counterparty to buy the stablecoins and exchange them into fiat currency for customers, this "proprietary exchange" activity will very likely require a separate VA Dealing licence in future, and can no longer be handled incidentally on the grounds that the MSO licence covers foreign currency exchange.
The same logic applies to custody. If a payment platform generates a custody wallet for a merchant, with the private key stored on the platform's server, and the merchant must have the platform sign in order to transfer funds, the platform is in fact controlling the customer's virtual assets. The future VA Custody regime will impose strict requirements on such services, including separate capital, decentralized key management, and segregation of hot and cold wallets. Many payment teams assume during product design that "managing keys for customers" is a good way to enhance user experience, but often overlook that under the regulatory logic this is directly equivalent to trust or custody business. If a company does not want to bear the heavy compliance costs of custody, adopting a non-custodial architecture, or connecting to a third-party institutional-grade custodian that is already compliant, is usually the more prudent path.
Compare your own product item by item
Listing together the functions the company plans to provide is often more useful than simply counting licences. The table below places common business activities alongside the corresponding scope of permission, making it easier to compare against your own product: which are part of the payment process itself, and which already extend into virtual asset dealing, asset custody, stablecoin issuance, or merchant financing.

Figure: Comparison of Hong Kong crypto payment business activities and corresponding licensing scopes
Conclusion
For companies preparing to do crypto payments in Hong Kong, the licensing assessment need not start with "how many licences does Hong Kong have". What needs to be clarified is a few specific arrangements: who is responsible for fiat currency exchange and cross-border collection and payment, whether the platform has formed a balance that can continue to be spent, whether the company itself buys and sells virtual assets, who holds the wallets and private keys, and whether money is lent to merchants.
Once broken down, the relationship between the licences is not so complicated: MSO and SVF are usually the regimes that payment products must assess first; VATP and the Stablecoin Issuer Licence enter the core analysis only when the company itself operates a trading platform or issues stablecoins; VA Dealing and VA Custody currently still depend on legislative progress; and TCSP and the Money Lenders Licence depend on whether the company actually provides trust or corporate services, or provides financing to merchants.
Therefore, the most worthwhile thing to do before launch is not to list all the licences, but to map out the fund flows, asset control, and customer relationships clearly, and then compare them item by item against the scope of permission. Only in this way can you know whether the existing design can go live directly, which functions need to be narrowed, and which issues should be dealt with after the new regime and detailed rules are clarified.
Reference sources: Hong Kong Customs "Guideline on Licensing of Money Service Operators" (MSO); Hong Kong Monetary Authority "Guideline on Licensing of Stored Value Payment Facilities" (SVF); Hong Kong Securities and Futures Commission "Handbook on Licensing of Virtual Asset Trading Platforms" (VATP); joint circular of the Hong Kong Securities and Futures Commission and the Hong Kong Monetary Authority "On Virtual Asset-Related Activities of Intermediaries"; Hong Kong's "Stablecoins Ordinance" and other public regulatory materials.